
What Original Medicare does not cover
Original Medicare (Parts A and B) covers hospital stays, physician services, outpatient care, and many medical supplies. However, it does not pay 100% of those costs. Beneficiaries are responsible for the Part A hospital deductible, daily coinsurance for extended hospital stays, the Part B annual deductible, and 20% coinsurance on most Part B services after the deductible is met.
That 20% coinsurance has no cap under Original Medicare alone. A serious illness or extended hospital stay can produce bills that add up quickly. For many seniors on fixed incomes, this is a real financial concern. Medigap policies exist specifically to limit that exposure.
See our guide to senior health coverage options for a broader look at what Medicare and its alternatives cover.
How Medigap policies work
A Medigap policy is purchased from a private insurance company, but the federal government standardizes the benefits each plan type must include. There are ten plan types, each identified by a letter: A, B, C, D, F, G, K, L, M, and N. An insurer cannot change what a Plan G covers; only the premium and customer service differ between companies selling the same letter.
When you receive care, Medicare pays its share first. Your Medigap plan then pays some or all of the remaining costs, depending on which plan type you hold. For example, Plan G covers the Part A deductible, coinsurance, and hospice care coinsurance, as well as Part B coinsurance and foreign travel emergency care (up to plan limits). The one cost Plan G does not cover is the Part B deductible.
Plan F availability after 2020
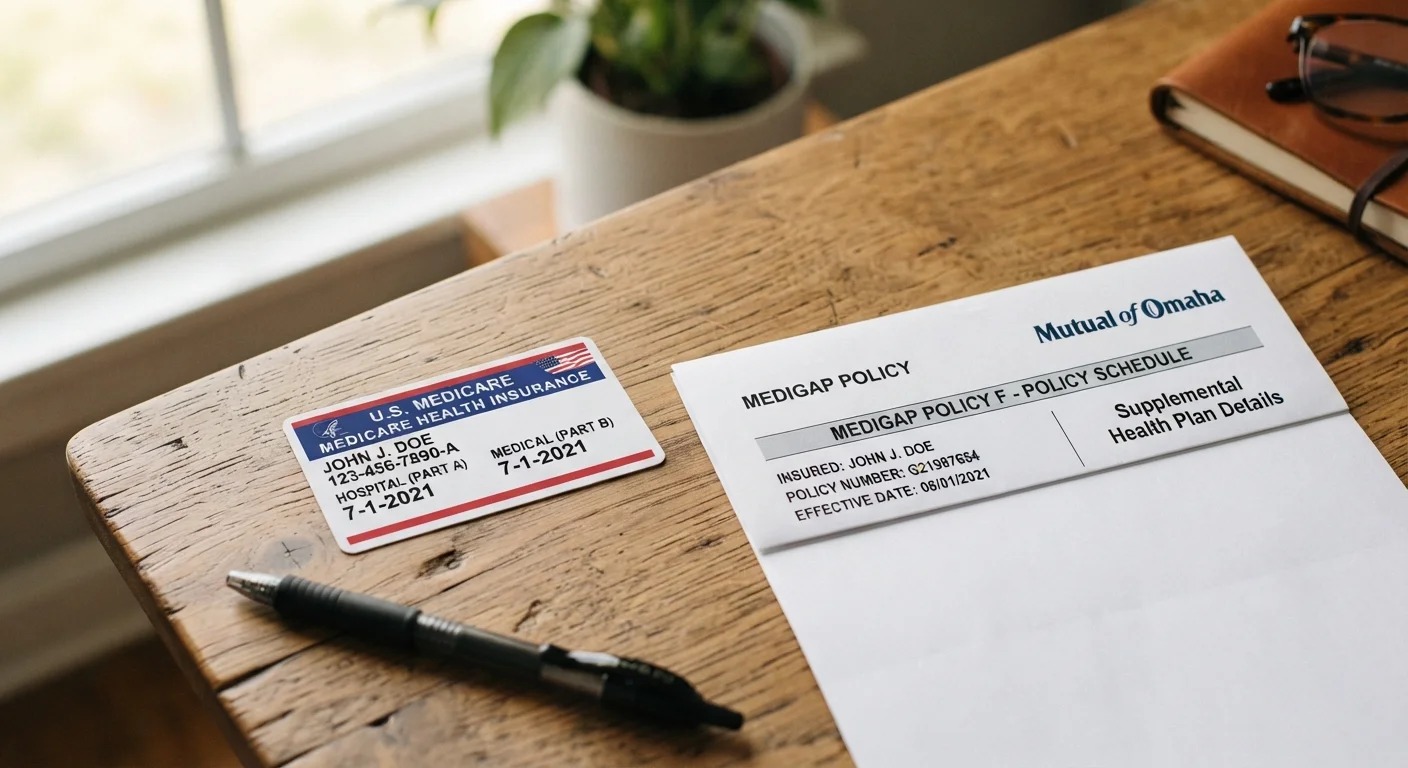
Plan F was historically the most comprehensive Medigap option because it covered the Part B deductible. A 2015 law barred new Medicare enrollees (those eligible on or after January 1, 2020) from purchasing Plan F. If you were already enrolled in Plan F before that date, you can keep it. Those newly eligible for Medicare should look at Plan G as the broadest option currently available to them.
Plan F covers the Part B deductible and is sometimes called the most comprehensive Medigap option available. However, it is only available to those who were eligible for Medicare before January 1, 2020. If you became eligible on or after that date, Plan G is generally the broadest option open to you.
Enrollment timing and medical underwriting
Timing matters significantly with Medigap. Your six-month Open Enrollment Period begins on the first day of the month in which you are both 65 or older and enrolled in Medicare Part B. During this window, a private insurer must sell you any Medigap plan it offers at standard rates, regardless of your health history.
Once that window closes, insurers in most states can use medical underwriting. That means they can review your health records, charge you higher premiums, or decline to sell you a policy based on pre-existing conditions. A small number of states have additional protections; check your state's insurance department for local rules.
20%
Part B coinsurance owed by Medicare beneficiaries
Original Medicare requires beneficiaries to pay 20% coinsurance on most Part B services, with no annual out-of-pocket maximum under Original Medicare alone.
10
Standardized Medigap plan types available
The federal government standardizes Medigap into ten lettered plan types (A through N, with some letters discontinued), each covering a defined set of cost-sharing items.
6 months
Medigap Open Enrollment Period length
Beneficiaries have a six-month window starting when they turn 65 and enroll in Part B, during which insurers cannot deny coverage or charge more due to health history.
Costs and premium pricing methods
Medigap premiums vary by plan type, insurer, and where you live. Beyond those variables, the pricing method an insurer uses affects how your premium changes over time.
- Community-rated: Everyone in the plan pays the same premium regardless of age.
- Issue-age-rated: Your premium is based on your age when you first buy the policy and does not automatically rise as you get older.
- Attained-age-rated: Premiums start lower but increase as you age. This is the most common method and can result in meaningfully higher costs in later years.
Comparing pricing methods alongside the monthly premium amount gives a clearer picture of long-term cost. You can compare Medigap plans available in your area through Medicare's official Plan Finder tool at medicare.gov.
If you are weighing whether Medigap fits your situation or whether a Medicare Advantage plan makes more sense, the financial assistance programs overview for seniors may also be relevant if cost is a primary concern.
This article is for general informational purposes only and is not personalized insurance or financial advice. Coverage rules, plan availability, and premiums vary by state and insurer. Read actual policy documents carefully and consult a licensed insurance agent or Medicare counselor (such as a State Health Insurance Assistance Program, or SHIP, counselor) before making coverage decisions.