
What a budget tune-up actually means
A budget is not a one-time document. It is a working plan that should reflect how money actually moves in your life right now. When it no longer does, small imbalances grow: overdraft fees appear, credit card balances inch up, and savings targets stall without an obvious cause.
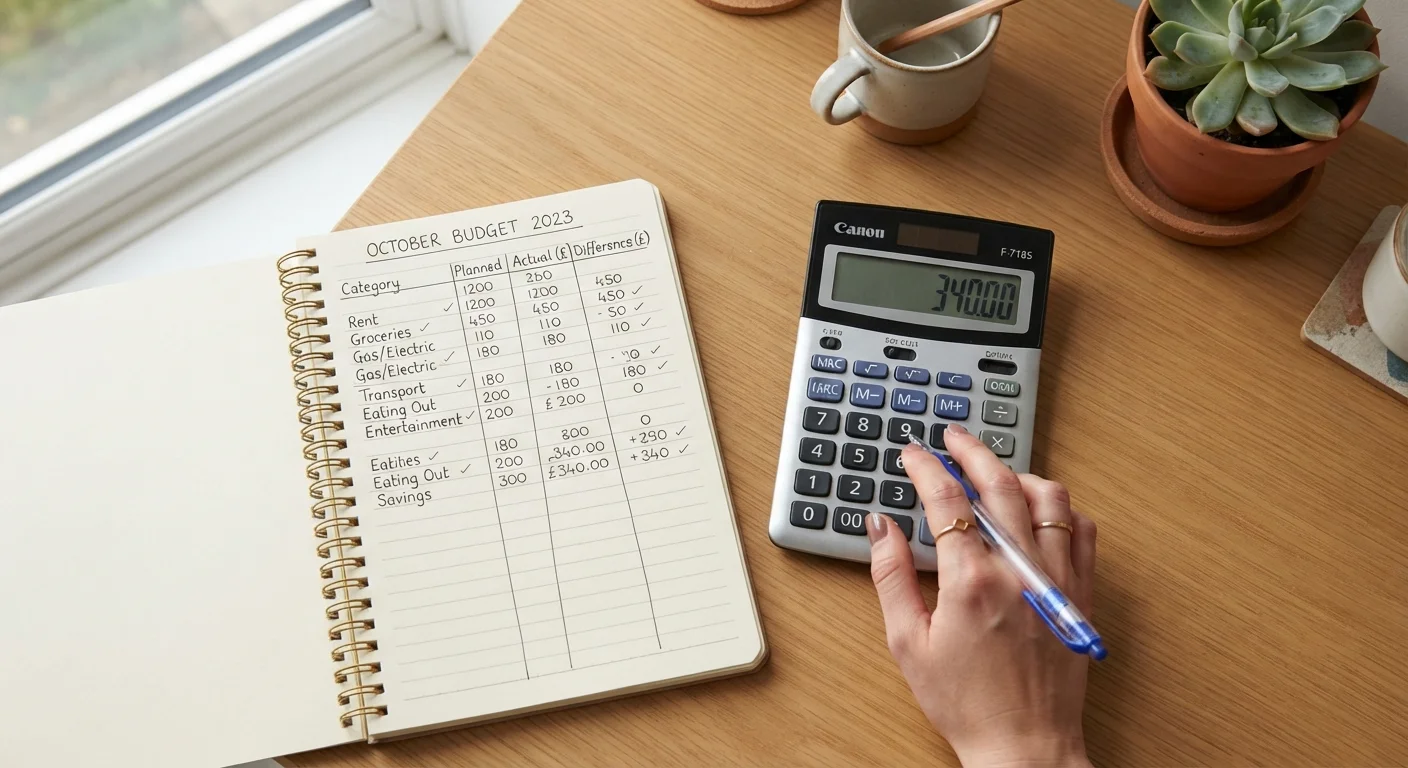
A tune-up means comparing what your budget says should happen against what your bank statements show actually happened. The gap between those two numbers is where the problems live. The mistakes below are the most common reasons that gap widens over time.
This article is general financial information and education, not personalized financial advice. For decisions specific to your situation, consult a licensed financial professional.
Common budget mistakes and how to fix them
Each of the following mistakes has a clear cause and a concrete fix. Reading them together can help you identify which ones apply to your current plan.
Treating your original budget as permanent rather than as a starting point.
Why it happens: Building a budget takes effort, so many people avoid revisiting it once it is done. Life changes steadily, but the budget document does not change with it.
Ignoring small recurring charges that accumulate into a significant monthly total.
Why it happens: Streaming services, app subscriptions, and auto-renewing memberships are easy to forget because the charges are small individually and post automatically.
Budgeting based on gross income rather than take-home pay.
Why it happens: Gross income is the number on a job offer or pay stub header, so it sticks in memory. Taxes and deductions can reduce that figure by 20 to 30 percent or more.
Leaving irregular expenses out of the monthly plan.
Why it happens: Annual insurance renewals, car registration, medical copays, and holiday gifts do not appear every month, so they feel like surprises when they arrive.
Setting savings contributions at whatever is left over rather than allocating them first.
Why it happens: Spending tends to expand to fill available cash. When savings come last, they absorb any overruns in other categories.
Failing to update the budget after a significant income or expense change.
Why it happens: A raise, a new rent payment, or a paid-off loan each shifts the balance, but many people absorb the change unconsciously rather than deliberately adjusting their plan.
If you are building a budget for the first time or starting over after a long gap, the practical framework for monthly budgeting covers the foundational structure before you apply these corrections.
When budget problems show up elsewhere
Budget gaps rarely stay contained. Carrying a credit card balance to cover shortfalls is one of the most common downstream effects. Before assuming a card is the problem, check whether the budget has a structural gap that the card is quietly filling. The common credit card myths article separates which card habits actually cost money from those that are commonly misunderstood.
Subscription and bundled service costs are another frequent source of budget creep. If you pay for bundled internet, TV, or phone service, understanding when bundles save money and when they do not can help you decide whether those line items are pulling their weight.
1 in 3
Americans with no monthly budget
According to the National Foundation for Credit Counseling's annual financial literacy survey, roughly one-third of U.S. adults report not keeping a monthly budget.
$219
Average monthly subscription spend per household
A 2022 C+R Research study found U.S. consumers underestimate their monthly subscription spending by roughly 2.5x, averaging $219 per month across all services.
A budget that has drifted out of alignment is not a failure. It is information. The correction is a review, a few updated numbers, and a realistic plan for the month ahead.