Reviewing your accounts monthly catches errors and unauthorized charges before they compound.
Comparing actual spending to your budget shows where your plan is holding and where it is not.
A monthly check-in is a good time to confirm that automatic savings transfers ran as intended.
Recurring subscriptions are worth auditing each month because costs and usage change over time.
This checklist covers spending, savings, debt, and account security in one structured pass.
Why a monthly review matters
A budget is only useful if you compare it against what actually happened. Without a regular review, small overspending patterns go unnoticed, unauthorized charges sit unchallenged, and savings goals drift. A monthly check-in gives you a fixed point to assess where your money went and decide whether your current plan still fits your situation.
If you have not built a spending plan yet, the practical budgeting framework covers how to map income and categorize expenses before running this checklist. If you have been through a few monthly reviews and notice the same problems repeating, signs your budget needs a tune-up describes when a deeper revision makes sense.
A monthly review does not need to be complex. Thirty minutes and a few account statements are enough to stay on track.
This article provides general financial information and education. It is not personalized financial advice. For guidance specific to your circumstances, consult a licensed financial professional.
What you need before you start
Gather your materials before working through the checklist. Having everything in one place prevents the review from stalling halfway through.
Required
Bank and credit card statements
Use these to verify every transaction and confirm your actual spending by category.
Required
Monthly budget or spending plan
Compare what you planned to spend against what you actually spent.
Required
Debt account summaries
Check current balances and confirm minimum payments were applied correctly.
Optional
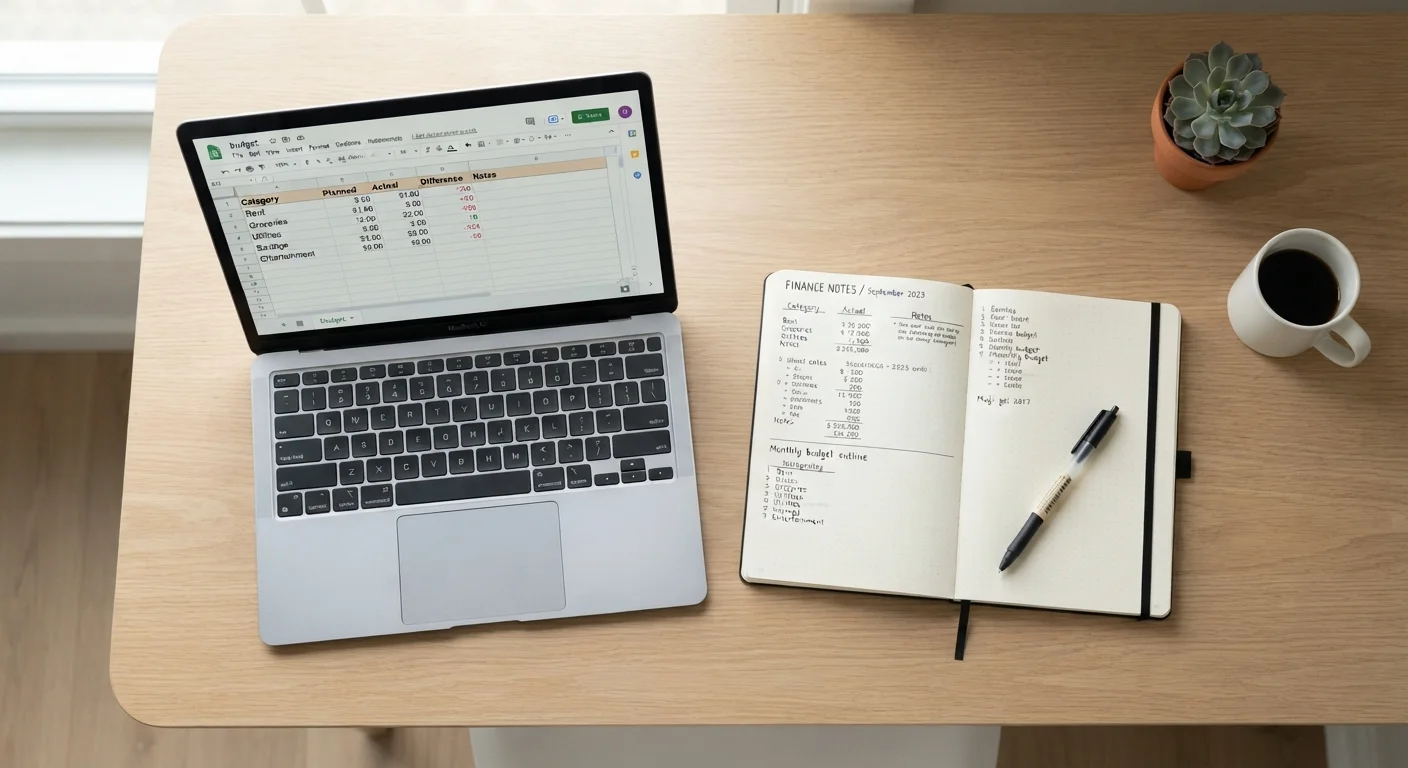
Spreadsheet or budgeting app
Record notes from your review and track month-over-month patterns.
The monthly check-in checklist
Work through each group in order. The categories build on each other: catching account errors first means your spending totals will be accurate when you compare them to your budget.
Account and transaction review
Log in to every bank and credit card account and scan all transactions from the past month for anything unfamiliar or incorrect.Must
Flag any duplicate charges, fees you did not expect, or transactions you cannot identify, and contact the institution to dispute or clarify them promptly.Must
Confirm that all scheduled bill payments posted on the correct date and for the correct amount.Must
Spending vs. budget
Pull your actual spending by category (groceries, housing, transportation, dining, entertainment) and compare each figure to what your budget allowed.Must
Note any category where you spent more than 10 percent above your plan, and write down one likely cause.Should
If you consistently overspend a category, adjust next month's budget to a more realistic figure rather than leaving an unworkable target in place.Should
Savings and transfers
Verify that any automatic transfers to savings or emergency fund accounts ran and posted in the correct amounts.Must
Check your emergency fund balance and note how many months of essential expenses it currently covers.Should
If you have a specific savings goal (travel, home repair, large purchase), update your progress tracker with the current balance.Nice to have
Debt and credit
Confirm that minimum payments on all loans and credit cards were received and applied, and that no late fees were assessed.Must
Record the current balance on each debt account so you can see whether balances are moving in the right direction over time.Should
Review any variable-rate account (such as a credit card or adjustable-rate loan) to check whether the interest rate changed since last month.Should
Subscriptions and recurring costs
List every recurring charge that appeared on your statements this month and confirm you are still actively using each service.Should
Cancel or pause any subscription you have not used in the past 30 days and note the expected savings in next month's budget.Nice to have
End-of-month notes
Write two to three sentences summarizing how the month went financially: what held to plan, what did not, and one adjustment to carry into next month.Should
Set a calendar reminder for your next monthly check-in before you close out your statements.Nice to have
What to do with what you find
A completed checklist is useful only if you act on what it surfaces. If you found unauthorized transactions, contact your financial institution to dispute the charges and request a review of your account security settings. If spending ran over budget in multiple categories, decide whether the budget figures need updating or whether spending habits need adjustment. The distinction matters: a budget set too low for your actual fixed costs will fail every month regardless of behavior.
Monthly reviews also reveal patterns across larger spending areas. If your transportation or housing costs are rising, that may connect to decisions covered in other areas of your financial life. The auto coverage and cost resources and home services guides can provide context when those line items look high.
Keep your written notes from each review. After three to four months, the notes will show whether your adjustments are working or whether a more substantial change to your financial plan is needed.
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.