
Why starting with no credit is its own situation
Having no credit history, sometimes called being "credit invisible," is not the same as having a low credit score. A low score means a lender has seen evidence of missed payments or high debt. No history means there is simply no file yet. Lenders cannot assess risk without data, so they may decline applications or charge higher rates until a track record exists.
The Consumer Financial Protection Bureau (CFPB) has estimated that tens of millions of Americans fall into a credit-invisible or unscorable category. This situation is common among young adults, recent immigrants, and people who have used only cash or debit for years.
Building a credit profile requires opening accounts that report to the major credit bureaus and then using those accounts responsibly over time. There is no shortcut, but the process is straightforward once you understand which tools are designed for it.
What you will need
How to build your credit profile step by step
Check whether a credit file already exists
Before opening any new account, request your credit reports from all three major bureaus (Equifax, Experian, and TransUnion) at AnnualCreditReport.com, the federally authorized source for free reports. If no file exists, the bureau will say so. If a thin file does exist, review it for errors before proceeding.
Open a secured credit card
A secured credit card requires a refundable cash deposit, which typically becomes your credit limit. You use the card for small purchases and pay the balance in full each month. The card issuer reports your payment activity to one or more credit bureaus, creating a payment history in your file.
When comparing secured card options, look at whether the issuer reports to all three bureaus, the annual fee, and whether the account can graduate to an unsecured card after responsible use.
Consider a credit-builder loan
Credit-builder loans work differently from conventional loans. The lender holds the loan amount in a secured account while you make monthly payments. Once you finish paying, you receive the funds. Throughout the term, the lender reports your payments to the credit bureaus. Many credit unions and some community banks offer these products specifically for people new to credit.
Ask to be added as an authorized user
If a family member or trusted person has a credit card with a long, positive payment history and low utilization, asking them to add you as an authorized user can transfer that account history to your credit file. You do not need to use the physical card for the history to appear. The primary cardholder remains fully responsible for the balance.
Pay every bill on time, every month
Payment history is the single largest factor in most mainstream credit scoring models. Even one missed payment can set back a new file significantly. Set up autopay for the minimum payment as a safety net, then manually pay the full statement balance before the due date. Apply this discipline to every credit account you open.
Some services, such as certain rent-reporting and utility-reporting programs, allow on-time non-credit payments to appear on your credit file. These programs vary in which bureau they report to and may charge a fee, so review the terms before enrolling.
Monitor your file and wait for a scoreable record
Most scoring models require at least one account that is six months or older before generating a score. During this window, continue using your accounts lightly and paying on time. Review your credit reports periodically for errors or unfamiliar accounts, and dispute inaccuracies with the relevant bureau in writing if you find them.
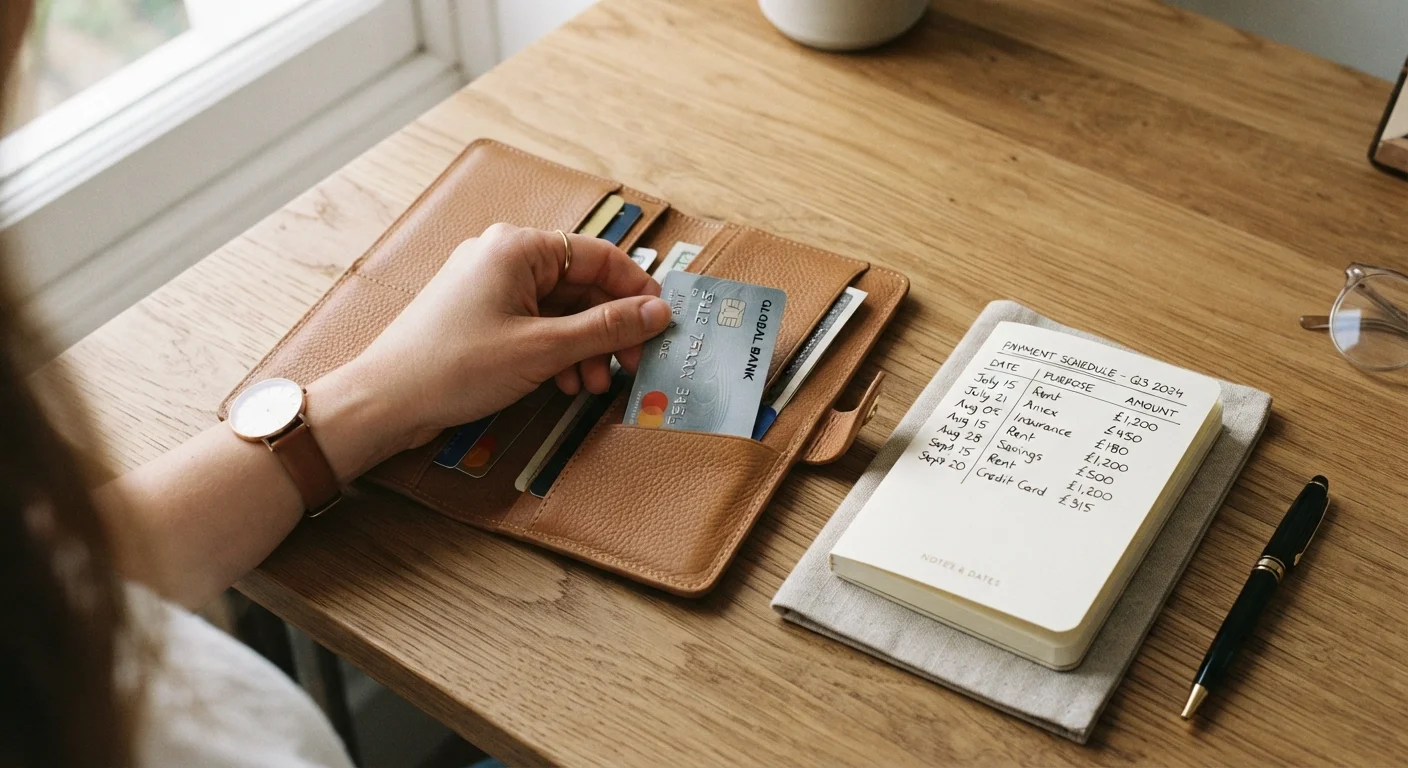
Once you have at least one scoreable account open for six months, check your reports again to confirm everything is accurate. From that point, responsible habits compound over time, and your file will reflect the full length of your account history.
Credit also affects more than borrowing. Landlords, some employers, and in most states, auto and home insurers may review credit information during their processes. Understanding this connection can add context to why building credit matters beyond just loan applications. For more on one specific downstream effect, see how credit history can factor into auto insurance rates.
This article is for general informational purposes only and does not constitute personalized financial or legal advice. Consult a licensed financial professional for guidance tailored to your circumstances.
Common missteps to avoid early on
Opening too many accounts in a short period generates multiple hard inquiries on your file and can thin out your average account age. Start with one or two products and give them time to mature before applying for more.
Closing a secured card too soon, once a deposit is returned, removes that account's history from your active file and can affect your utilization ratio if you carry balances elsewhere. Before closing any account, consider whether keeping it open with no balance costs you anything beyond an annual fee.
Carrying a balance from month to month does not help your score and adds interest costs. The idea that you need to carry a balance to build credit is a persistent myth. Several other credit card myths can cost you money if left unchecked, and separating fact from fiction early will save you real dollars over time.