
How the no-cost rule works
The Affordable Care Act, signed in 2010, requires most health insurance plans to cover a specific set of preventive services without charging you anything at the time of service. No copay, no coinsurance, and the cost does not count against your deductible, provided you see a provider in your plan's network.
The requirement applies to plans sold on the ACA marketplace, most employer-sponsored plans, and Medicaid expansion programs. It does not automatically apply to every plan. Grandfathered plans (those that existed before the ACA and have not changed significantly) are exempt. So are short-term health plans, which operate outside many standard ACA rules.
One detail worth knowing: the no-cost coverage applies to the preventive service itself. If your doctor addresses a separate health concern during the same visit, that portion may be billed as a diagnostic service and cost-sharing may apply. Letting your provider know in advance that you are there for a preventive visit can help avoid surprise charges.
Before your appointment, confirm the billing code
Ask your provider's office to confirm the visit will be billed as preventive, not diagnostic. A quick conversation before the appointment can prevent unexpected charges after it. If you plan to discuss an ongoing health concern, ask whether that should be a separate visit.
What counts as a covered preventive service
Three federal bodies set the list of services that plans must cover. The U.S. Preventive Services Task Force (USPSTF) recommends screenings and counseling for adults. The Advisory Committee on Immunization Practices (ACIP) sets vaccine recommendations. The Health Resources and Services Administration (HRSA) covers additional services for women and children.
Common services on the covered list include:
- Blood pressure screening
- Cholesterol and lipid screening
- Colorectal cancer screening (colonoscopy and stool-based tests)
- Mammograms and cervical cancer screenings
- Diabetes screening for adults at higher risk
- Lung cancer screening with low-dose CT for adults who meet specific smoking history criteria
- Depression screening
- Routine vaccines, including flu, shingles, and pneumonia shots
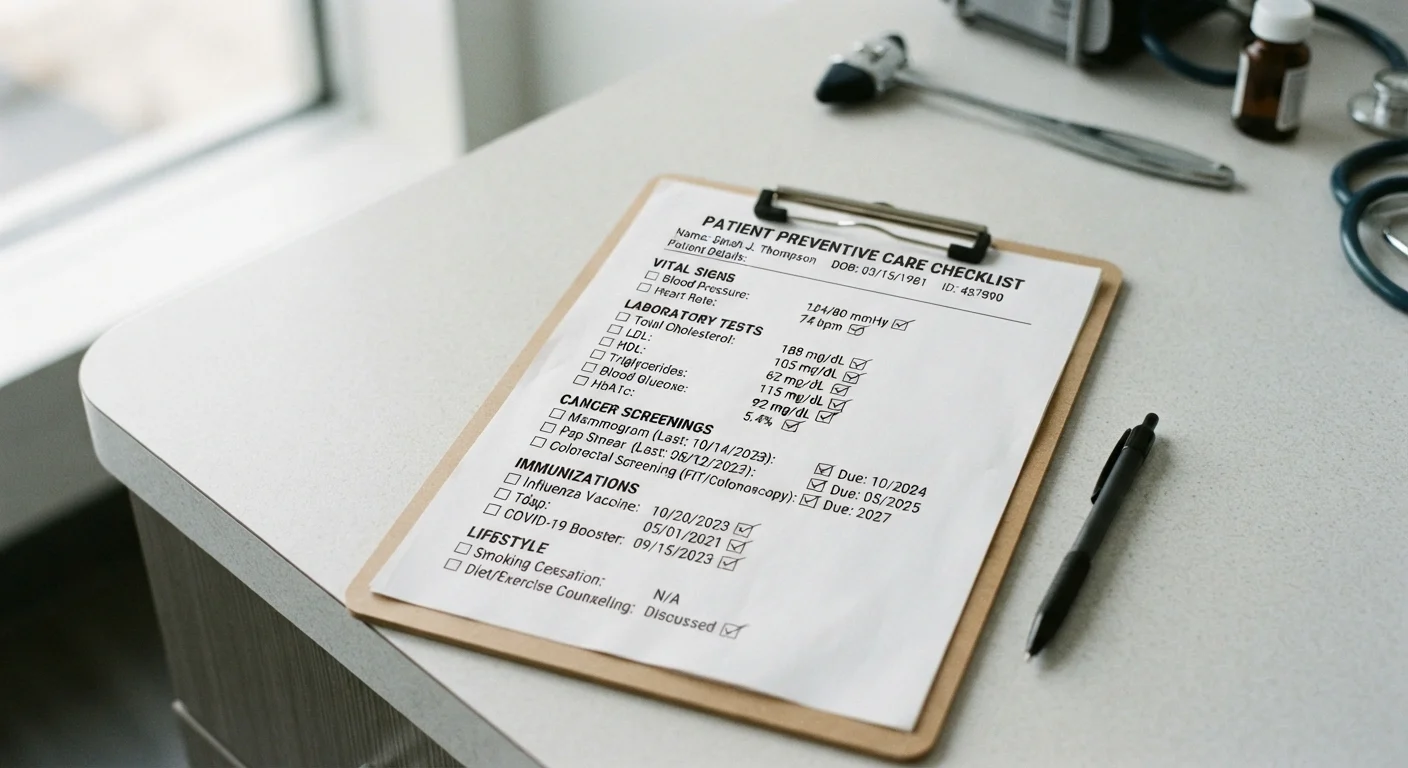
Which services apply to you depends on your age, sex, and health history. A 45-year-old woman has different recommended screenings than a 65-year-old man. Your primary care provider can walk you through what is currently recommended for your situation.
Why many people still skip these services
Despite the no-cost structure, a substantial share of adults do not use preventive care regularly. The reasons vary. Some people assume a screening will still cost money, so they avoid scheduling it. Others feel well and see no reason to go. Transportation, work schedules, and difficulty finding an in-network provider also get in the way.
Skipping screenings does not mean a condition is not developing. Many serious conditions, including high blood pressure, elevated cholesterol, and early-stage cancers, produce no noticeable symptoms for years. Screenings exist precisely because waiting for symptoms is often waiting too long.
If you are on Medicare, preventive coverage follows different rules depending on the part involved. The Medicare Parts A, B, C, and D guide explains which services fall under which part and what cost-sharing, if any, might still apply.
Steps to use your preventive benefits
Before scheduling, confirm that your provider is in your plan's network. Call the member services number on your insurance card if you are unsure. When you call to make the appointment, describe it as a preventive wellness visit so the office codes it correctly from the start.
Bring a list of any health concerns you want to discuss separately. Mixing preventive and diagnostic topics in a single visit is common, but knowing which is which helps both you and your provider keep billing accurate.
After your visit, review your Explanation of Benefits (EOB) statement from your insurer. If a charge appears for a service you believed was preventive, contact your insurer to ask for a review. Billing errors happen, and insurers have a process for disputes.
This article is for general informational purposes only and does not constitute medical or insurance advice. Coverage rules vary by plan and by state. Consult a licensed insurance professional and a qualified healthcare provider for guidance specific to your situation.