
Why open enrollment deserves your attention
Open enrollment is the one time each year when you can switch health plans, add dependents, or adjust your coverage without needing a qualifying life event. Letting the window pass without reviewing your options means you stay on your current plan by default, even if your health needs or finances have changed.
The process feels complicated to many people, but it follows a predictable pattern. You gather information about your current health use, compare plan structures and costs, confirm that your providers and medications are covered, and then enroll. This walkthrough breaks that process into concrete steps.
What you will need
This article is general health insurance information and is not personalized insurance, financial, or medical advice. Coverage terms, costs, and eligibility vary by plan and provider. Consult a licensed insurance agent or broker for guidance specific to your situation.
Step-by-step walkthrough
Work through these steps in order. Each one builds on the information you collect in the previous step, so skipping ahead can leave gaps that cost you money later.
Pull together your health records from the past year
Before you compare any plans, gather information about how you actually used your coverage. Look at your Explanation of Benefits statements or your insurer's online account to see how many times you visited a doctor, filled a prescription, or used any specialist care. This gives you a realistic baseline rather than a guess.
Write down every prescription you currently take, including the dosage. Drug formularies (the lists of covered medications) vary between plans, and a medication that costs $10 a month on one plan can cost significantly more on another.
Know your enrollment window
Open enrollment dates differ depending on where you get coverage. For Marketplace plans under the Affordable Care Act, the federal window typically runs from November 1 through January 15, though some states that run their own exchanges set different dates. Employer plans set their own windows, often in the fall. Medicare's Annual Enrollment Period runs October 15 through December 7 each year.
Missing your window generally means you cannot change plans until the next enrollment period unless you have a qualifying life event, such as losing other coverage, getting married, or having a child. Check the exact dates for your situation and add a calendar reminder well before the deadline.
Understand the plan types you will see
Most plans fall into a few common structures. An HMO (Health Maintenance Organization) requires you to choose a primary care doctor and get referrals to see specialists. A PPO (Preferred Provider Organization) lets you see specialists without a referral and gives you some coverage even for out-of-network providers, usually at a higher cost. An EPO (Exclusive Provider Organization) works like a PPO for the network but typically offers no out-of-network coverage at all.
For a side-by-side look at how HMOs and PPOs handle networks and referrals, see our HMO vs. PPO comparison.
Compare total costs, not just premiums
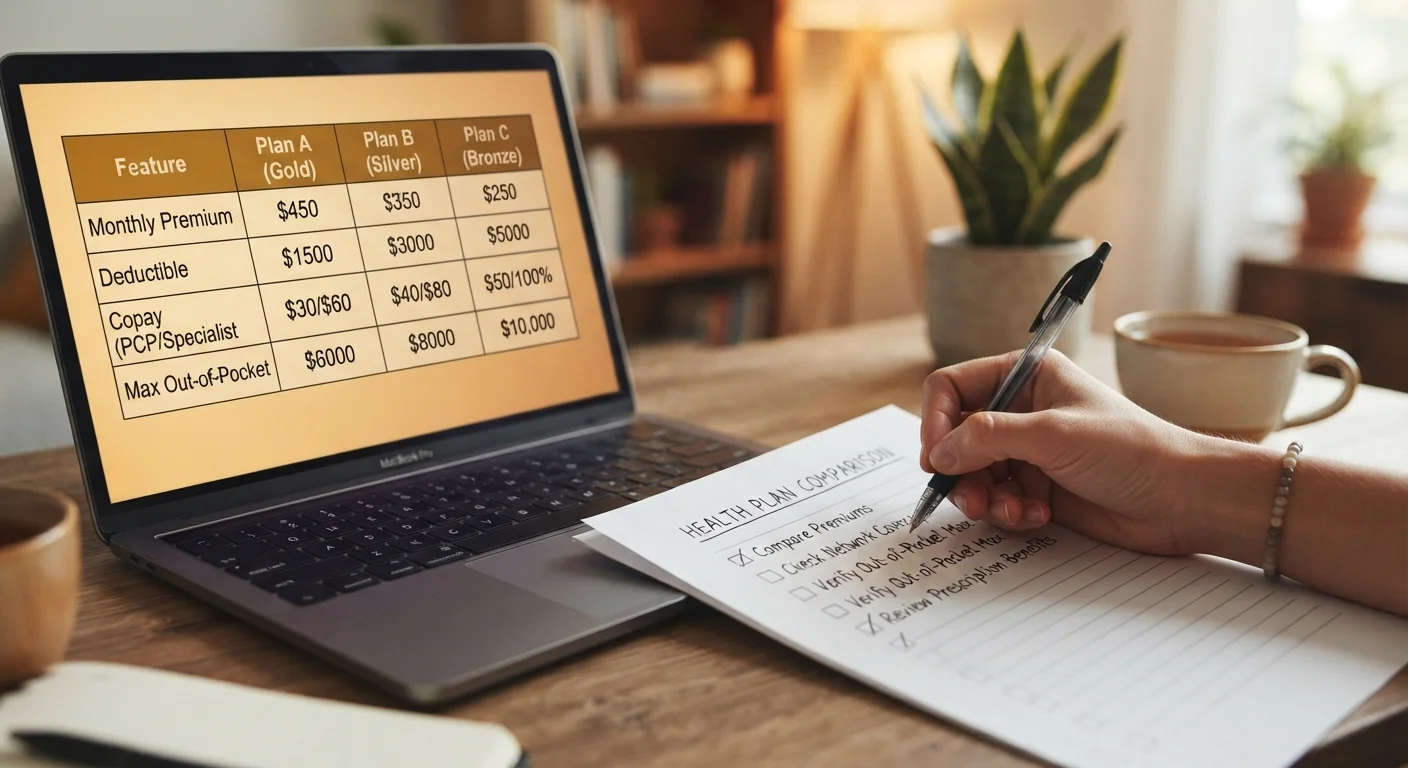
The monthly premium is the amount you pay to keep coverage active, but it is rarely the only significant cost. Look at these figures for each plan you consider:
- Deductible: the amount you pay before the plan starts covering most services
- Copay and coinsurance: your share of each visit or service after the deductible
- Out-of-pocket maximum: the most you would pay in a year before the plan covers 100 percent of covered costs
A plan with a low premium often has a higher deductible. If you use a lot of care, a slightly higher premium with a lower deductible may cost you less overall by year's end.
Verify your doctors and drugs are covered
Every plan maintains a network of contracted providers. Before you enroll, go to the plan's provider directory and confirm that your primary care doctor, any specialists you see regularly, and your preferred hospital are listed as in-network. Provider directories can change, so check the current version rather than relying on last year's information.
Do the same for medications. Look up each drug you take in the plan's formulary. Note which tier it falls under, since higher tiers carry higher cost-sharing. If a medication is not on the formulary, ask whether an exception process exists before assuming you will have to switch drugs.
Check subsidy eligibility if you are using the Marketplace
If you buy coverage through HealthCare.gov or a state exchange, you may qualify for a premium tax credit based on your household income and size. The Marketplace's built-in calculator estimates this when you enter your information. Eligibility rules have changed in recent years, so even if you were not eligible before, it is worth checking again.
If you have access to employer coverage, the calculation is more involved. Our article on employer coverage versus Marketplace plans walks through how to think about that comparison.
Enroll and confirm your coverage
Once you have chosen a plan, complete your enrollment through the appropriate channel: your employer's benefits portal, HealthCare.gov, your state exchange, or Medicare's website. After submitting, you should receive a confirmation number or email. Keep that record.
Watch for your new insurance card in the mail or available for download, and confirm the effective date of coverage. If you are switching plans, do not cancel any existing coverage until you have written confirmation that the new plan is active.
If you have experience comparing insurance in other areas, the general approach is similar to what our auto insurance walkthrough covers, though the specific terms and categories differ.
Tools that make comparison easier
Having the right resources open while you work through your options reduces the time spent searching for basic information.
HealthCare.gov plan finder
Browse Marketplace plans, check subsidy eligibility, and compare costs side by side if you do not have employer coverage.
Your employer's benefits portal
Access plan options, contribution rates, and enrollment forms if coverage is offered through your job.
Medicare Plan Finder (medicare.gov)
Compare Medicare Advantage and Part D drug plans if you are 65 or older or otherwise eligible for Medicare.
Your pharmacy's drug pricing tool
Verify that your medications are on a plan's formulary and check which tier they fall under before you enroll.
Use last year's costs as a starting point
Your insurer's year-end summary shows exactly what you spent on premiums, deductibles, and copays. Comparing that total against the projected costs of a new plan gives you a concrete number to work with rather than an estimate. Many insurer websites display this under 'claims history' or 'spending summary.'